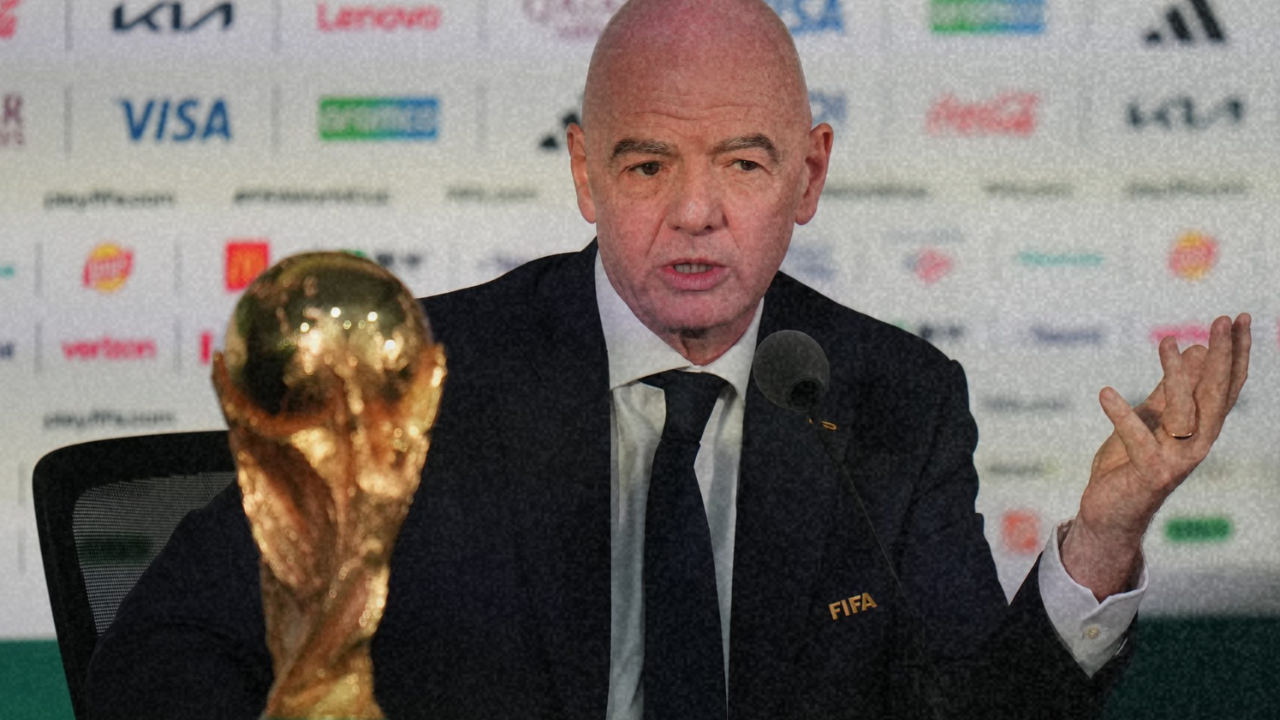
A proposed US$4.2 billion investment would give outside shareholders a long-term claim on FIFA’s commercial operations while promising far larger payments to its 211 member associations.
FIFA has proposed turning the commercial business surrounding the World Cup into a partly investor-owned company.
The governing body said Tuesday it wants to create FIFA Forward Enterprise, a FIFA-owned subsidiary that would consolidate its broadcasting, sponsorship, ticketing, licensing and tournament-delivery operations. FIFA would retain control, but outside investors could purchase minority, non-controlling interests worth up to 20 percent of the company.
The target is US$4.2 billion based on an initial valuation of US$20 billion.
FIFA says the proposal would unlock more money for football development. UEFA says it crosses a line that football’s governing institutions should not cross.
The disagreement is not really about ownership of the trophy or the rules of the game. FIFA is not proposing to give investors authority over qualification, refereeing, sporting regulations or the international match calendar.
It is proposing to give them a long-term equity claim on the business that makes those competitions valuable.
What FIFA Forward Enterprise Would Own
FIFA describes FIFA Forward Enterprise as a dedicated commercial subsidiary. The organization’s broadcast rights, sponsorships, ticketing and licensing would be brought together with the operational delivery of its tournaments.
That distinction matters. The proposal is not a literal sale of the World Cup. FIFA would remain the governing body, retain majority representation on the subsidiary’s board and keep exclusive authority over competitions and sporting decisions.
Outside investors would nevertheless own part of the company positioned to benefit from the growth of FIFA’s tournament portfolio.
Every additional broadcast package, sponsorship agreement, hospitality programme, ticket sale and commercial product would contribute to the subsidiary’s value. So would decisions that increase the number or scale of FIFA events.
An investor would not need the right to rewrite the Laws of the Game to benefit from more matches, larger tournaments or additional broadcast windows. The sporting calendar would remain under FIFA’s formal control, while the commercial returns created around that calendar would be shared with private shareholders.
FIFA says those shareholders would have no operational role and that all net benefits generated through the subsidiary would be reinvested in football worldwide.
The central question is whether those assurances are enough. A long-term investor does not need direct sporting authority to develop an interest in commercial expansion. Ownership creates expectations, and expectations can shape the environment in which future decisions are made.
The Funding Offer to 211 Associations
FIFA has connected the proposed investment structure to a large expansion of development funding.
Each of FIFA’s 211 member associations would be offered access to as much as US$20 million in one-off capital through a new FIFA Fast Forward Programme. FIFA says the optional funding could support stadiums, training centres, coaching, national teams, competitions, grassroots football and the women’s game.
Separately, FIFA wants to increase regular FIFA Forward funding for the 2027–2030 cycle from the currently budgeted US$8 million to US$20 million per association. The planned allocation would then rise to US$22 million for 2031–2034 and US$24 million for 2035–2038.
Those are two different commitments. The first is an optional pool of immediate capital financed through the proposed investment. The second is a larger recurring development allocation based on FIFA’s expected commercial growth.
FIFA is presenting them together because the argument for outside investment depends on what the new money could finance.
That creates a political mechanism as well as a financial one.
FIFA’s associations are not passive customers. They are the voting members of a Swiss non-profit association and the effective collective owners of the governing body. A majority of them, along with the FIFA Council, would have to approve the new structure.
Yet the associations do not approach that vote from equal economic positions.
For the largest federations, FIFA development money is a small part of a much larger football economy. For smaller associations, it can determine whether facilities are built, national teams travel, coaches are trained and domestic competitions operate.
The proposal therefore asks FIFA’s members to judge a long-term restructuring while showing them an immediate expansion of the funding many rely on.
That does not prove anyone is being bought. It does mean the incentives cannot be separated from the governance question.
FIFA’s Ownership Contradiction
FIFA’s proposal contains an unusual contradiction.
Its member associations already collectively own the organization in the only sense available under its non-profit structure. Each association has one vote, regardless of the commercial size of its national football system.
The new subsidiary would place private investors inside the commercial layer of an organization whose members already possess formal governing authority.
FIFA would still control the subsidiary. The investors would own only a minority. But the members would be approving a corporate structure that gave outside capital a claim on revenue generated by competitions conducted under their collective authority.
At the same time, those members would be promised access to far more development funding.
Formal voting equality does not erase financial dependence. Every association would have one ballot, but not every association would have the same freedom to reject an offer worth tens of millions of dollars.
This is the strongest reason to examine the structure before reducing the story to personalities or political connections.
Why UEFA Is So Angry
UEFA responded immediately, accusing FIFA of putting football’s soul and governance up for sale.
Its objection has substance. Private shareholders would acquire an ongoing financial interest in the commercial growth of the World Cup and FIFA’s other competitions. That could create pressure for more inventory, more frequent events and greater extraction from broadcasters, sponsors, ticket buyers and host markets.
UEFA is not a neutral observer.
FIFA and UEFA compete for calendar space, broadcast attention, sponsorship money and authority over the clubs and players whose labour sustains both institutions. A stronger FIFA commercial operation could challenge the economic position of European club football and UEFA’s own national-team competitions.
UEFA can therefore oppose private investment on a defensible governance basis while also protecting its institutional position.
Those motives are not mutually exclusive.
The Kushner Connection
Thrive Eternal, a permanent-capital vehicle launched by Joshua Kushner’s Thrive Capital, is expected to lead the proposed investor group.
Joshua Kushner is the brother of Jared Kushner, Donald Trump’s son-in-law. That connection will intensify scrutiny because FIFA and Trump have developed a close public relationship around the 2026 World Cup.
Reuters reported that Jared Kushner is not a potential investor.
The more important issue is not whether this can be turned into another Trump-family scandal. It is why FIFA believes any private investor should receive equity in a commercial business built on competitions sustained by players, supporters, broadcasters, public authorities and host communities.
The investor’s identity matters. The structure matters more.
What Happens Next
FIFA says the proposal will move into consultation with its 211 associations and the FIFA Council. It will proceed only if a majority of associations support it and the required regulatory changes are approved.
That process should determine more than whether FIFA can raise US$4.2 billion.
It should establish what rights investors would receive, what obligations the subsidiary would carry, how future revenues would be divided and how FIFA would prevent commercial return from influencing sporting expansion.
FIFA’s case is that a dedicated business can generate more value and spread it more widely. UEFA’s case is that football’s governing institutions should not create permanent commercial obligations to outside shareholders.
Both arguments lead to the same question.
Who is the World Cup’s commercial value for?
FIFA’s answer is that private capital can help the governing body distribute more money across the global game.
The proposal now has to prove that giving investors a share of the business does not also give the business a stronger claim on the future of the sport.
Sources
- FIFA, July 28, 2026 — Original proposal, subsidiary structure, valuation, investor terms, funding commitments and approval process.
- Reuters, July 28, 2026 — Initial reporting on the proposal, UEFA’s immediate response, Thrive Eternal and the Jared Kushner distinction.